

Ava Finance
4.7

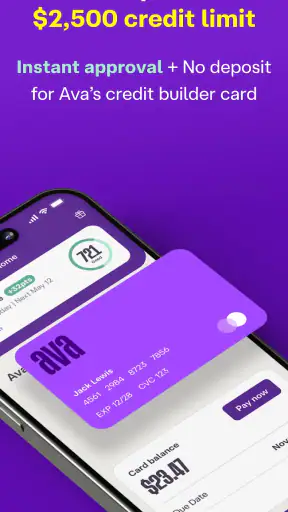
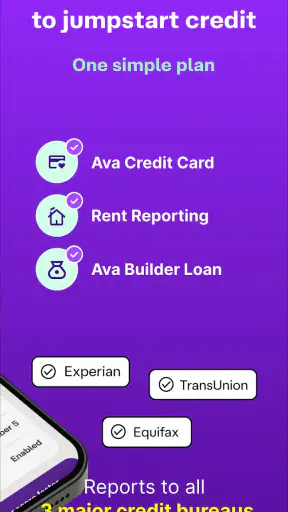
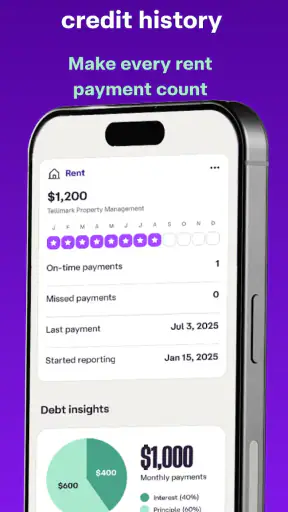
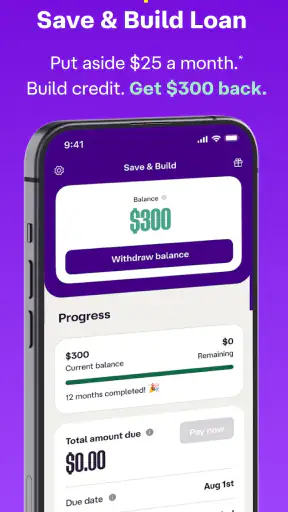
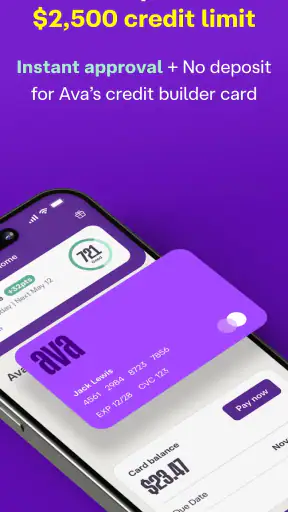
Managing credit from a phone sounds convenient, but the real test is what happens when you are standing in a shop, checking a financial decision between errands, or trying to understand a change without a laptop nearby. I spent time with Ava Finance, a free finance app from Ava Finance, Inc., and found that its value depends as much on a reliable connection and a willingness to follow through as it does on the app itself. It is built around the idea of helping people build credit quickly, but that goal needs to be understood as a process rather than a shortcut.
The app is aimed at everyday users who want a more approachable way to engage with their credit situation. Its Everyone age rating makes it broadly accessible, and its popularity is reflected in an average rating of 4.7 from around 17 thousand ratings, with more than 500 thousand installs. Those figures do not replace personal research, but they do suggest that Ava has reached a substantial audience. My overall impression is positive for someone who wants a focused credit-building tool on a phone, although it is not the right replacement for every financial service.
How Ava feels when your connection is part of the experience
Network-dependent moments are central, not incidental
The first thing I would tell a new user is that a finance app should be treated differently from a calculator or notes app. Ava is used for information that can affect decisions, so the experience is naturally tied to current account information, progress views, and actions that need to be processed correctly. When the network is stable, moving through the app feels much more reassuring because you can review what is happening before making a choice.
That connection matters most when you are checking whether an action has gone through. A brief loading pause in a finance app creates more uncertainty than the same pause in a casual game. I found myself paying attention to whether a screen had fully refreshed before leaving it, especially after completing an important step. That is a useful habit with Ava: do not assume that tapping a button means the process is finished until the app visibly confirms the next state.
This is also where expectations need to be realistic. A credit-building app can organize information and guide you through its own workflow, but it cannot turn an unstable mobile signal into a dependable financial connection. If you are in a basement shop, on a crowded train, or switching between Wi-Fi and cellular service, I would avoid making a rushed decision. Wait until the relevant page loads properly, then check the result again later if anything looks incomplete.
A practical phone scenario
Imagine that I am applying for an apartment and want to review my credit-related progress while I am away from home. I can open Ava during a break, look over the information available in the app, and decide whether I need to spend more time reviewing my situation. That is the kind of mobile convenience that makes sense: a short check that helps me plan, rather than an attempt to solve my entire financial life in a few taps.
If the connection drops at that moment, the best response is not repeated tapping. I would take a screenshot only for my own temporary reference if appropriate, close the app if it becomes unresponsive, and return when the connection is stable. I would not treat a partially loaded page as a final answer. This sounds obvious, but it is an important distinction between using a finance tool responsibly and using an entertainment app where a failed action has little consequence.
Mobile contexts where the app makes the most sense
Ava is most useful in short, intentional sessions. I would use it at home when I have enough time to read the wording carefully, then use it on the go for quick checks. That split works better than trying to complete every financial task in a noisy environment. The phone format is helpful because credit questions often arise unexpectedly, but convenience should not encourage careless decisions.
The app also suits people who prefer a single, focused place to revisit their credit-building activity instead of searching through email, browser tabs, and paper records. I like that kind of concentration. It reduces the mental effort of remembering where I last checked something. At the same time, I would still keep my broader financial records elsewhere. Ava can be part of a routine, but it should not become the only place where I understand my money.
For someone who rarely has dependable mobile service, the experience may be frustrating. The issue is not simply waiting for a screen to load; it is the uncertainty that comes with not knowing whether the latest information is available. I would recommend using the app primarily when connected to a trusted, stable network, particularly for setup and any action that changes your account position.
What to do when something fails
One of the more useful habits I developed was separating three situations: a page that is still loading, an action that has completed, and an action whose status is unclear. Those states can feel similar on a small screen, especially when you are distracted. With Ava, I would pause after any important action and look for a clear change in the interface before trying anything else.
If a screen freezes, I would first check the connection rather than immediately repeating the action. Then I would reopen the relevant area and see whether the result has appeared. Repeating a financial action simply because the first attempt did not display quickly can create confusion. This is a small but significant trade-off of mobile finance: the phone makes access easy, while the compact interface makes patience more important.
Another sensible step is to record the time and nature of a problem for yourself. I am not suggesting that every minor delay needs a formal report, but a short note can help distinguish a one-off network issue from a recurring problem. If the app behaves normally after reconnecting, the original failure was probably situational. If the same workflow repeatedly produces unclear results, I would stop and seek help before continuing.
The current version is 5.1.6626, and keeping an app like this updated is a practical part of recovery planning. Updates can improve compatibility and stability, but I would still avoid installing one at the exact moment I need to complete an urgent financial task. My preference is to update when I have time to reopen the app, confirm that it launches correctly, and review the relevant screen without pressure.
Using data carefully on a mobile plan
Finance apps are not where I want to waste mobile data, but I also would not make decisions based on an old screen just to save a small amount of bandwidth. My approach is simple: use a reliable Wi-Fi connection for initial setup, detailed review, and updates when possible, then use cellular service for brief checks when necessary.
There is a useful middle ground between constant refreshing and never checking. Refreshing repeatedly during a poor connection does not make information more current; it only makes the experience more stressful and may consume more data. I prefer one deliberate check, followed by a pause. If the result is unclear, I wait for a better connection rather than turning the same request into a loop.
I would also avoid opening Ava while several other apps are actively using the connection, especially during travel. Closing unnecessary streaming or download activity can make a short finance session feel more responsive. This is not a special feature of Ava, but it is a realistic way to improve the experience without changing phones or plans.
Where it stands beside usual alternatives
The usual alternatives depend on what you are trying to accomplish. A bank app is generally the natural place for checking balances and transactions, while a browser can be better for comparing several services or reading longer explanations. A credit-monitoring service may provide a wider view of credit information, and a spreadsheet can be more flexible for building a personal budget.
Ava’s appeal is narrower and more practical: it gives users a phone-centered route into credit building rather than asking them to assemble a system from unrelated tools. That focus is a strength for beginners who feel overwhelmed by broad financial dashboards. It is less compelling for someone who already has a detailed credit routine and wants comprehensive budgeting, investment tracking, or a full account-aggregation experience in the same place.
I would not choose Ava solely because it is free. Free access removes an obvious barrier, but the important question is whether its approach fits your goal. If you want help staying engaged with credit building and prefer guided mobile access, it deserves consideration. If you need a complete financial command center, you will probably still need other apps or services alongside it.
Who benefits most from the focused approach
I think Ava is best for a person who knows that credit matters but has struggled to turn that knowledge into a repeatable routine. The app can serve as a prompt to pay attention, review progress, and make more informed choices. It may also suit a younger adult beginning to manage credit independently, provided they are willing to read terms carefully and understand that building credit is not instant.
It is less suitable for someone looking for a guaranteed score increase or a way around responsible financial behavior. No app can substitute for understanding obligations, checking dates, and avoiding decisions that do not fit a personal budget. I would also steer away from relying on it if your main need is detailed debt planning or a complete view of household cash flow. A dedicated budgeting tool may be more useful in that situation.
One non-obvious advantage of a focused app is psychological: a smaller task can be easier to repeat than a full financial review. Instead of opening a large dashboard and feeling buried in categories, I can approach one credit-related objective at a time. The trade-off is that this simplicity may hide the wider context unless I deliberately review my bank accounts, bills, and budget elsewhere.
Questions I would answer before installing it
Is it genuinely free to start? Yes, Ava is listed as a free app. I would still read every screen carefully before accepting any financial arrangement, because “free app” describes the download and access model, not a promise that every possible financial consequence disappears. That distinction is important with any credit product.
Can it replace a bank app? I would not treat it that way. A bank app remains the better place for ordinary banking tasks, while Ava is more specifically oriented toward credit building. Using both may be sensible if you want to connect everyday money management with a more focused credit routine.
Is it useful without reliable internet? I would not plan around that. The most important experience depends on current information and completed actions, so I would use it when the connection is dependable. If you spend much of your day offline, this may not be a comfortable primary tool.
Does a high user rating guarantee that it will fit me? No. The 4.7 average and broad adoption are encouraging, but finance is personal. Someone who wants a guided, focused experience may appreciate Ava more than someone who expects detailed budgeting, investing tools, or every financial account in one place.
What should I do before trusting the app with an important decision? I would confirm that the latest screen has loaded, read the wording instead of skimming it, and give any action time to show a completed state. I would also compare the information with my own records when the decision matters. That workflow is slower than tapping through quickly, but it is the safer way to use a mobile finance app.
My connectivity verdict
After using Ava Finance, I see it as a useful, focused companion for people who want to work on credit building from a phone. Its free availability, Everyone rating, and clear finance focus make it approachable, while the involvement of Ava Finance, Inc. gives the product a defined identity rather than making it feel like a generic budgeting notebook. The app’s strongest quality is its ability to make a potentially intimidating subject feel like something I can revisit in short sessions.
Its biggest limitation is also tied to that mobile format. When the connection is weak or an action does not immediately show its result, I have to slow down and verify what happened. That is manageable, but it means I would not use it casually in every environment. A stable connection, careful reading, and a willingness to keep separate financial records make a noticeable difference.
My recommendation is to try Ava if you want a dedicated credit-building routine, not a complete replacement for your bank or budget tools. Use it at home for thoughtful setup and review, then reserve mobile checks for moments when the network is reliable. If that workflow matches the way you manage money, the app can be a practical addition. If you need offline certainty, extensive financial planning, or a broad all-in-one dashboard, another category of tool will likely serve you better.
For me, the final decision comes down to expectations. Ava is not valuable because it makes credit effortless; it is valuable when it helps turn attention into consistent action. That makes it worth considering for a beginner or anyone rebuilding a routine, while experienced users with a more complete system may find its focused scope limiting.
4.7
1.69K Reviews
Pros
- Clear overview of borrowing
- lending
- and portfolio activity
- Supports automated yield strategies for hands-off DeFi users
- Useful market data for comparing available lending opportunities
- Non-custodial design lets users retain control of their wallet
- Streamlined interface makes DeFi tools easier for newcomers
Cons
- DeFi transactions may involve network fees and variable gas costs
- Smart-contract risks can lead to loss of deposited funds
- Available features may depend on the connected blockchain network
- Variable rates can change quickly and affect expected returns
- Some advanced tools may feel confusing without DeFi experience


